Introduction: A High-Voltage Month for Indian Equities
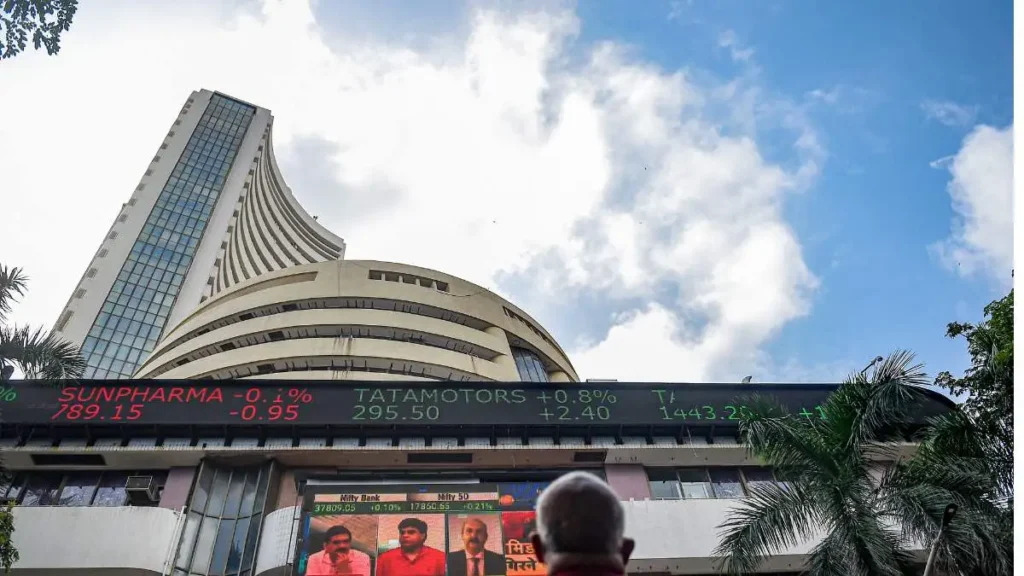
October 2026 was anything but ordinary for the Indian stock market. The month brought a rollercoaster of emotions, dramatic swings in major indices, and sharp moves driven by both global and domestic factors. Investors saw everything from intense selling, quick recoveries after brutal corrections, and renewed anxieties fueled by energy prices and foreign capital shifts.
Let’s break down what really happened in October, which sectors felt the heat, who were the big winners and losers, and what might be coming next as the calendar moves on.
Sharp Swings and the Dussehra Break: Index Movement Through October
The first two weeks of October were intense. After a tough start with big sell-offs, the Nifty 50 Index roared back mid-month. There was a strong recovery, and by Friday, October 16, the Nifty closed at 23,146.15, a weekly gain of 2.78% the best in six months. This boost was mainly because of good earnings signs coming from IT companies and some positive bets around possible tax reliefs.
But markets don’t stay happy for long. On Monday, October 19, profit booking kicked in, especially in private sector banks and consumer stocks. The BSE Sensex dropped 876 points (1.17%) to close at 73,852.90, and the Nifty 50 fell 257 points (1.11%) to 22,888.95.
October 20 was a market holiday for Dussehra. Trading paused, which added a rare moment of stillness after all that excitement.
Key Index Levels at a Glance
- BSE Sensex: 73,852.90
- Nifty 50: 22,888.95
- BSE Midcap: 15,842.73
- BSE Smallcap: 6,826.87
- Nifty PSU Bank: 7,185.40 (actually up, outperforming the broader market)
- USD/INR: 84.12 (Rupee remained under pressure)
Main Forces Driving the Market
Private Banks’ Margin Pain vs. PSU Banks’ Resurgence
The battle between private banks and their state-owned (PSU) counterparts was apparent. Private lenders like Axis Bank, HDFC Bank, and ICICI Bank faced squeezed profits. Their net interest margins (the money banks make on loans minus their cost for deposits) kept shrinking as they fought hard for new deposits. As a result, Axis Bank’s shares tumbled about 4%, and there were ripples across financial stocks.
Meanwhile, PSU banks outshined. Improving asset quality and steady loan growth fueled a jump in the Nifty PSU Bank Index. State Bank of India, to name one, managed to keep its bad loans at multi-year lows, which helped drive its shares up by more than 1% that session.
Energy Prices and Their Ripple Effects
It was impossible to ignore global events. Brent crude, which hovered above $105 per barrel, hit India right where it hurts fuel import bills. A costly import bill pushed the trade deficit higher and kept the rupee weak at 84.12 to the dollar.
Higher oil prices also translated to more expensive raw materials for manufacturers (think cars, paint companies, the works), which squeezed profits and temper growth hopes. The Reserve Bank of India held off on any plans for interest rate cuts with inflation concerns piling up.
Foreign Investors Taking Money Out, But Domestic Investors Stepping In
October was marked by a tug-of-war between foreign and domestic investors. Foreign Portfolio Investors (FPIs) were net sellers, mostly due to high US bond yields, which topped 5%. A lot of money flowed out of Indian stocks and into US treasuries and other Asian markets seen as cheaper.
At the same time, Indian mutual funds got a huge boost from Systematic Investment Plans (SIPs), with monthly inflows over ₹24,000 crore. These domestic funds helped balance out foreign selling, especially by buying into PSU banks, metals, and infrastructure stocks.
Sectors: Who Led, Who Lagged?
Top Performers: IT, PSU Banks, Metals
IT stocks were the big winners. The Nifty IT Index jumped nearly 4% in a single session (October 16). Strong Q2 results, steady demand from overseas clients, and a stable dollar helped.
PSU banks, on the back of better asset quality, kept rising as well. JSW Steel and ONGC, both benefiting from global trends and home infrastructure growth, also closed October 19 in the green.
- Nifty IT Index (Technology Services): Up 3.9% in October.
- Nifty PSU Bank Index: Up 2.41% on October 19 alone.
- JSW Steel, ONGC, Adani Ports and L&T all posted gains, thanks to rising commodity prices and capital project execution.
The Laggards: Private Banks, Autos, FMCG
Private sector banks saw steep corrections, with Axis Bank leading the drop. High deposit costs and tighter margins hit hard. Even established names like ICICI and HDFC Bank saw heavy profit-taking.
Automobiles had a rough ride. Tata Motors, for example, was down over 3% as worries grew over slowing commercial vehicle demand and expensive inputs. Fast-Moving Consumer Goods (FMCG) stocks lagged too mainly due to stubbornly slow rural demand growth.
- Axis Bank: Down 3.85% to 4.19% in a single session.
- Tata Motors: Down 3.09%.
- Infosys: Down about 2.7% after a big run-up, mostly due to profit booking.
Technical Picture: Support, Resistance, and What Charts Say
Market at a Critical Juncture
As of October 19, the Nifty 50 stood at 22,888.95. That’s 2.5% below the recent high, and after breaking through the key 23,000 support, technical momentum shifted to sellers. The daily Relative Strength Index (RSI) slipped to 44.2, suggesting the index was close to oversold, but not yet appealing enough to lure big buyers back in droves.
Key Levels to Watch:
- Immediate resistance: 23,000 to 23,120. The market needs to climb above this range for bulls to feel confident again.
- Main support: 22,700. Below here, the next big defense is 22,450, near the 100-day simple moving average. If things turn ugly, that’s where buyers could show up.
- Long-term line in the sand: 21,800. If the index drops this far, it signals a real shift in trend.
What’s Happening in Derivatives and Institutional Flows?
Futures and Options: What the Smart Money Is Betting
NSE futures and options figures told an interesting story. The Nifty 50 put-call ratio fell to 0.78 after Monday’s sell-off, which means more traders were betting against the market. Most call options sat at 23,000 and 23,200, showing these are tough ceilings. Support from puts sat around 22,800 and lower suggesting if the market dips, that’s where the next round of support will try to hold.
The India VIX (the “fear gauge”) rose 4.8% to 14.85. Volatility was up, and traders were bracing for sharper moves ahead.
Outlook for the Rest of October: Three Scenarios
How things play out from here depends on a few key triggers. Here’s how most institutional investors are thinking:
- Bullish Recovery: If Nifty manages to climb back above 23,120, it sets the stage for a big move up toward 23,350 or even 23,500. This will probably need strong results from FMCG and auto companies and continued support from domestic buyers.
- Sideways Consolidation (Most Likely): More range-bound trading between 22,700 and 23,120, as markets digest earnings, and local mutual funds provide a steady stream of inflows to balance foreign selling.
- Bearish Retest: If oil prices go higher or something rattles global markets, a drop below 22,700 could drag the Nifty down to the 100-day average around 22,450. At that point, sentiment shifts decisively negative.
October 2026: Key Market Stats and Takeaways
- BSE Sensex Close: 73,852.90 (-1.17%) on October 19
- NSE Nifty 50 Close: 22,888.95 (-1.11%) on October 19
- October Weekly High (Nifty): 23,146.15, best in six months
- Top Sectors: IT (up 3.92%), PSU Banks (up 2.41%)
- Biggest Risks: Brent crude over $105, which keeps the rupee weak and inflation high
- Main Support: 22,700, then 22,450
- Key Resistance: 23,000, 23,120, 23,500
Conclusion: A Market Shaped by Contrasts
October 2026 underlined just how sensitive the Indian stock market is to both local news and bigger global forces. Narrowing profits for private banks, soaring oil prices, currency worries, and foreign capital flight surfaced quickly and rattled traders. Yet, the strength of domestic investors, better performance from PSU banks, and a strong run in IT gave plenty of reasons to stay optimistic.
In the weeks ahead, holding above 22,700 and watching domestic flows will be the keys for investors tracking risk and reward. With earnings still rolling in and energy markets on edge, there’s little sign the wild ride is over just yet. Always remember, as with any equity market, high volatility means opportunities and risks often come hand in hand.
This report is for information only. Investing in stocks is risky do your own homework or consult a trusted advisor before taking the plunge.